Greetings,
RBA Lifts Interest Rates
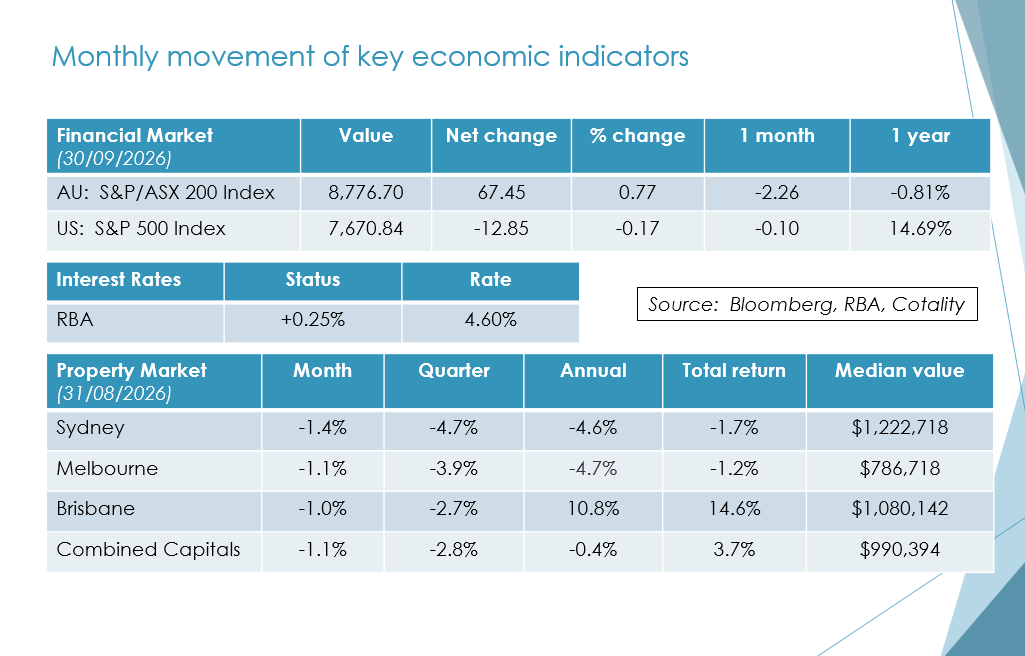
As expected, the RBA has increased interest rates in Australia by 25 basis points to 4.6%, making Australia the second-highest interest rate country in the developed world.
Advanced economy central bank policy rates (%)
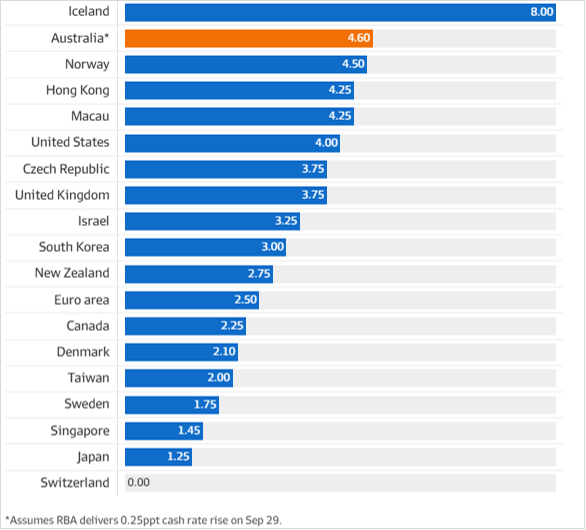
Source: Michael Read, AFR – Trading Economics
This is the highest cash rate in Australia in 15 years and has a significant impact on investment decisions, with the cost of borrowing increasing and making some marginal projects unviable. It also makes it harder for companies to employ staff, as a greater amount of their cash flow must be directed towards meeting interest payments.
At this stage, the futures market is predicting one further rate increase before Christmas. The RBA statement highlighted the ongoing conflict in the Middle East as one of its principal concerns, while also reflecting on the lack of productivity in the domestic economy, which has led to supply shortages, particularly in the construction sector. Click on the following link to view the Statement by the Monetary Policy Board: Monetary Policy Decision
Using interest rates to suppress economic activity is a very blunt instrument, damaging both discretionary and non-discretionary spending, while reducing the supply of available cash in the economy. An analogy would be pouring weed killer on a cricket ground that kills the weeds and the good grass in equal measure.
Ultimately, this needs to be a short-term solution, with interest rates falling later next year, otherwise the economy could quickly move into a policy-induced recession. The main sector now under pressure will be discretionary spending in retail, which is already being reflected in the share prices of listed consumer-facing companies. With mortgages and rent representing the largest non-discretionary expenses, we expect the property market to remain subdued until interest rates begin to decline.
AUGUST CPI
Adding to this narrative, the CPI for August was released 24 hours after the RBA’s decision and came in at an annualised rate of 4.0% and a monthly rate of 0.4%, which was broadly in line with market expectations.
The timing of the release is a good example of how regulators need to better coordinate the release of data so that more informed policy decisions can be made in a timely manner.
The principal drivers were, once again, domestic capacity pressures and increases in oil prices, which have flowed through to higher petrol prices due to the Iran war. This further reinforces the RBA’s unanimous decision by all nine members to raise interest rates.
Client Investment Decisions
The corollary of higher interest rates is the opportunity for net savers to earn a higher rate of return on guaranteed investments while taking a lower level of risk to meet their cash flow requirements.
Accordingly, guaranteed investments are becoming more attractive relative to the risks associated with buying equities. Both term deposit and annuity rates are approaching 6%, and we will look to de-risk portfolios where appropriate, particularly where attractive multi-year rates are available.
This may involve reducing exposure to fund managers specialising in smaller listed companies in Australia, which may struggle to access capital at competitive rates.
In aggregate, Australia has over $4.5 trillion in superannuation assets, with around 25% in the drawdown phase. Combined with deep capital markets, this should ensure payments continue to be made regularly and on time to clients in a risk-reduced manner.
Managing Private Credit Risk
Much of the lending to businesses, and particularly developers, is now undertaken by private credit providers rather than the traditional major banks.
Clearly, rising interest rates and falling property prices make this a riskier proposition. This is leading to tighter lending standards, which will restrict the availability of credit to the construction sector and reduce the supply of housing entering the Australian market, again placing upward pressure on rents.
Credit managers will naturally need to adopt a more conservative approach to underwriting projects. For listed entities, this may mean reviewing the carrying value of existing assets, particularly developments that have not yet been completed.
Several of the major credit funds have had to revalue their assets based on pressure from their auditors and trustees. Your own investments remain at the highest quality end of credit market but if there any fund related matters I will write to those of your effected separately.
The aggregate effect will be slower economic growth until a combination of improved productivity in the construction sector and lower interest rates restores business confidence.
Dwelling construction productivity in decline
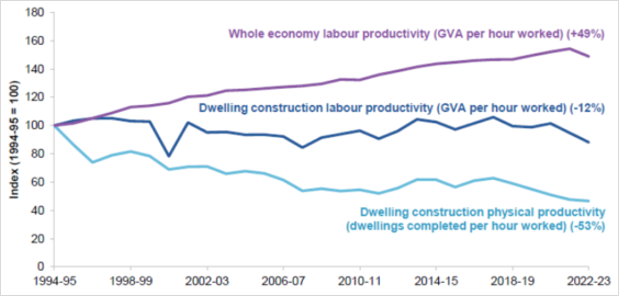
Source: Housing construction productivity: Can we fix it? Productivity Commission, Feb 2025
Australian Equity Markets
With the annual reporting season completed and dividends now being paid to shareholders, this was likely to be a period of consolidation.
The May Budget changes have encouraged listed companies to increase dividend payout ratios rather than reinvest in growth initiatives. As a result, one of the highest levels of dividends ever was paid in Australia during the past financial year, and this is likely to remain a feature of domestic investing for the foreseeable future.
These dividends appear sustainable, but are primarily being generated through cost reductions driven by automation and artificial intelligence rather than increased revenue growth.
Average dividend yields from the Australian share market
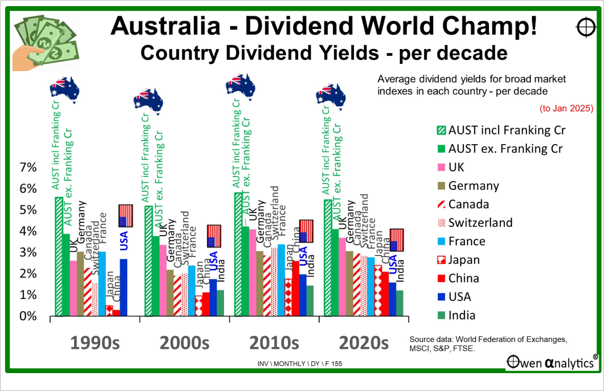
Source: Owen Analytics
The graph shows that Australian shares provide a higher level of dividends coupled with franking credits relative to its peers. At its most basic, invest in Australian shares for income and franking credits, but look overseas for growth.
Global Equity Markets
Another strong earnings season in the United States was primarily driven by the adoption of artificial intelligence, with GDP growth reaching 5%.
Major technology providers continue to invest heavily in data centres, including in Australia, to support their operations. In the short term, this investment may be inflationary. However, as these technologies become more widely adopted, they should reduce the cost of information and potentially become a deflationary force over the coming years.
There are legitimate concerns about the safe use of AI, including issues highlighted by the recent Medicare cyber incident in Australia. The obvious risk is that technology is advancing faster than society’s ability to manage it effectively.
Establishing appropriate safeguards to ensure AI is used for positive outcomes, particularly in areas such as medicine, rather than causing harm, has become a top priority for governments both in Australia and abroad.
Global annual investment in data centres, Base Case, 2015-2030
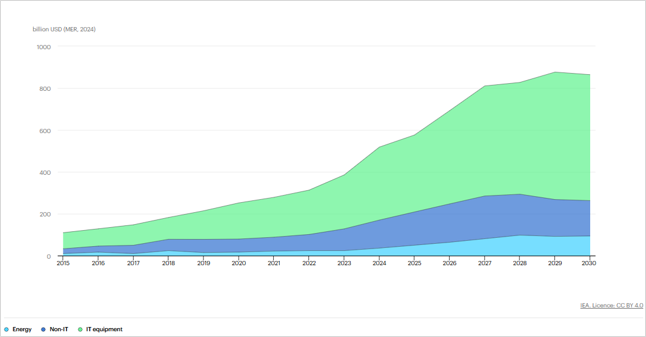
Sources: IEA (2024) analysis based on SemiAnalysis (2023 and 2025).
Domestic Property
As would be expected, a combination of four interest rate rises over the past 12 months and the changes to negative gearing and capital gains tax announced in the May Budget has led to a substantial decline in auction clearance rates and a steady reduction in property values across Sydney and Melbourne.
It may be that much of the bad news has already been priced into the market and that we are approaching the bottom of this cycle.
For those with flexibility around buying or selling property, it is probably prudent to wait until the full impact of these changes becomes clearer.
The long-term supply shortage remains in place, which over time should support higher property prices, particularly for properties located closer to CBD areas.
Future Elections
We have a state election in Victoria in November, followed by one in New South Wales in March. Meanwhile, in the United States, the midterm elections in November may have a material impact on President Trump’s ability to implement policy over the following two years.
For those following developments in the Middle East, Israel also has an election scheduled in October, which may influence its policies in the region.
Ultimately, successful governments generally require strong economies, which in turn rely on lower interest rates and higher productivity. These elections will therefore provide constituents with an opportunity to vote for change if they see fit.
Our News
As you would expect, we remain both focused and busy. Our client base broadly falls into two categories: those living on savings, who now have access to higher risk-free returns, and those seeking to accumulate wealth while managing mortgages, who may need to prioritise immediate expenses through careful cash flow management.
As a firm, we have navigated many economic cycles over the past 36 years and remain here to support you and your family, whatever your current circumstances.
We continue to receive excellent referrals from existing clients and have created additional capacity to ensure we can continue to serve them well.
With our thanks for your loyalty and support.
Sincerely,
Tony and Fiona
Please note this newsletter is of a general nature only.
ABN 42 060 673 814 • AFSL No. 407238